Highlands say study
p. 44 · Read in the full issue
confirms Raimi deposit's low cost status
HIGHLANDS Pacific Limited expects to go ahead with its $1.33 billion Ramu nickel joint venture in Papua New Guinea by the sec ond half of 1999, after a feasibility study confirmed the low-cost status of the pro ject.
The bankable feasibility study, prepared by Fluor Daniel and HA Simmons in joint venture, has forecast cash operating costs for the project will average US$l.3B per pound of nickel metal or US$lO per pound cobalt credit.
“At these cost levels, the project (will) be the world’s lowest cost producers,” said the managing director of the minerals explorer lan Holzberger.
Highlands Pacific holds a 65 per cent interest in Ramu and manages the project, with Nord Pacific Limited taking up the remaining stake.
Mr Holzberger said the forecast costs were seven US cents per pound less than the pre-feasibility study had indi cated, based on an US$B per pound cobalt credit.
“Significantly, there is potential to reduce the capital
cost by up to 10 per cent and the operating cost by up to 20 per cent by incorporating a number of potential design changes iden tified during an engineering review,” Mr Holzberger said in a statement.
“These opportunities are being actively pursued with the commissioning of addi tional pilot plant test work to prove the application of the changes”.
He said the study also confirmed Ramu’s potential as a long-life mine with production averaging 33,000 tonnes per annum of London Metal exchange class 1 nickel cathode and 3,200 tonnes per annum
of cobalt, as a pure cobalt sulphate. “The current ore reserve will support a 20 year mine life. However, the resource base indi cates that a mine life of 35 to 40 years is probable,” Mr Holzberger said.
He said project commitment was antic ipated in the second half of 1999, with first metal production expected at the end of 2001.
“We will need six to nine months to put the financing together,” Mr Holzberger said. He said the joint venture was looking
at a “shandy” of commercial bank debt, multi-lateral import/export agencies and equity funding.
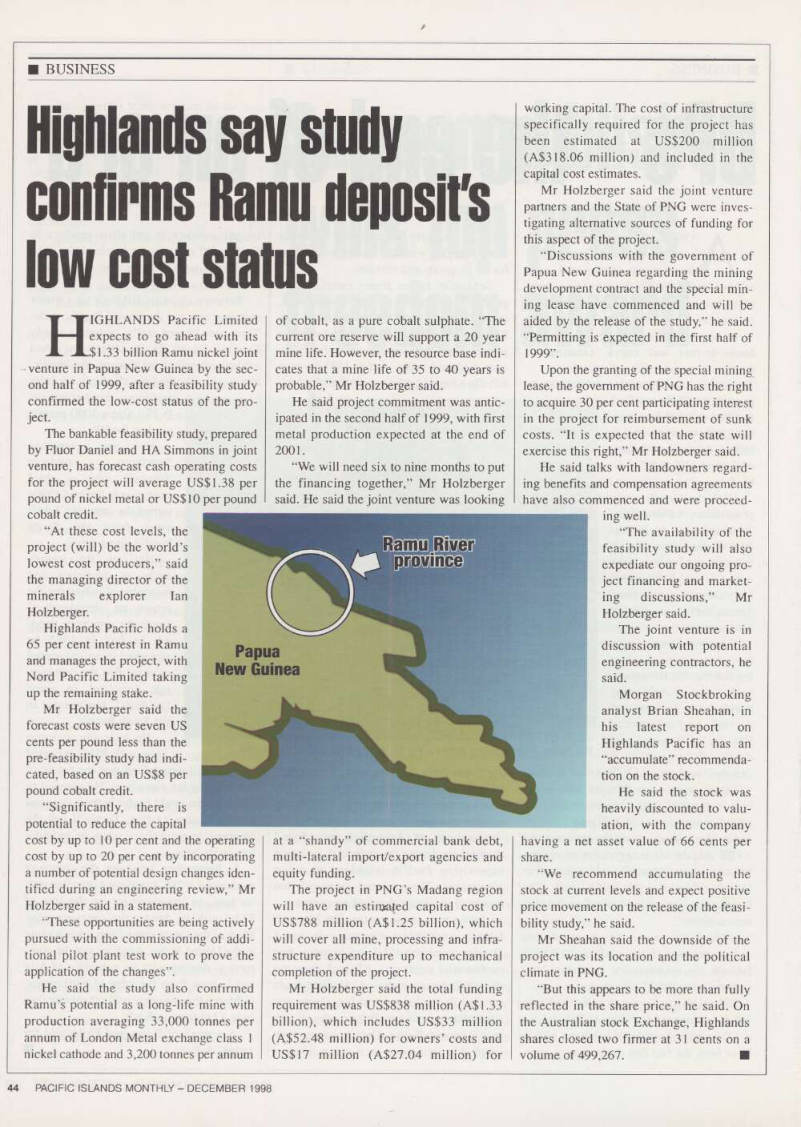
The project in PNG’s Madang region will have an estimated capital cost of US$7BB million (A 51.25 billion), which will cover all mine, processing and infra structure expenditure up to mechanical completion of the project.
Mr Holzberger said the total funding requirement was US$B3B million (A$ 1.33 billion), which includes US$33 million (A 552.48 million) for owners’ costs and US$l7 million (A 527.04 million) for
working capital. The cost of infrastructure specifically required for the project has been estimated at US$2OO million (A 5318.06 million) and included in the capital cost estimates.
Mr Holzberger said the joint venture partners and the State of PNG were inves tigating alternative sources of funding for this aspect of the project.
“Discussions with the government of Papua New Guinea regarding the mining development contract and the special min ing lease have commenced and will be aided by the release of the study,” he said.
“Permitting is expected in the first half of 1999”.
Upon the granting of the special mining lease, the government of PNG has the right to acquire 30 per cent participating interest in the project for reimbursement of sunk costs. “It is expected that the state will exercise this right,” Mr Holzberger said.
He said talks with landowners regard ing benefits and compensation agreements have also commenced and were proceed
ing well.
“The availability of the feasibility study will also expediate our ongoing pro ject financing and market ing discussions,” Mr Holzberger said.
The joint venture is in discussion with potential engineering contractors, he said.
Morgan Stockbroking analyst Brian Sheahan, in his latest report on Highlands Pacific has an “accumulate” recommenda tion on the stock.
He said the stock was heavily discounted to valu ation, with the company
having a net asset value of 66 cents per share.
“We recommend accumulating the stock at current levels and expect positive price movement on the release of the feasi bility study,” he said.
Mr Sheahan said the downside of the project was its location and the political climate in PNG.
“But this appears to be more than fully reflected in the share price,” he said. On the Australian stock Exchange, Highlands shares closed two firmer at 31 cents on a volume of 499,267. ■