Unfinished Agenda
pp. 16-17 · Read in the full issue
Why corporate and financial sector reforms must continue
By Sophie Hildebrand
By all accounts, it seems that Pacific island nations are on the path to recovery after the worst economic crisis since the Great Depression.
After two years of recession in Fiji, the country’s GDP grew by almost eight per cent last year. Papua New Guinea’s economic growth rate was above expectations at 3.9 per cent.
In the ten smallest Pacific countries (Cook Islands, Kiribati, Marshall Islands, Federated States of Micronesia, Nauru, Samoa, Solomon Islands, Tonga, Tuvalu, and Vanuatu) real GDP increased by a weighted average of 0.9 per cent, compared with 0.2 per cent in 1998 and 0.3 per cent in 1997.
But the Asian Development Bank has warned countries in its portfolio that the biggest risk facing the Asia-Pacific region now is complacency.
“As markets recover and foreign investors return, the momentum for further reform is weakened. With growing opposition from vested interests, the risks of backtracking are
high”.
It said corporate and financial sector reforms must continue in order to prevent a recurrence of the economic
nightmare.
In its annual publication, the Asian Development Outlook 2000, the ADB says the economic prospects of the Pacific, in the short to medium term, depend on the success of public sector reforms, sustained macroeconomic stabilisation and private sector
development.
“The region’s short-term recovery, as well as its long-term economic future, rests largely on how effectively and comprehensively the financial and corporate sector can be restructured.”
It said the short-term agenda needed to focus on asset management
companies and disposing of their assets.
The regulatory framework surrounding the purchase, management, transfer and sale of assets needed to be improved to make such practices easier.
This particularly applied to transfer taxes and recognising losses from the sale.
The private sector also needed to be involved in the restructuring process to help reduce the government’s fiscal obligation and ensure that management companies were as commercial as possible.
A crucial part of any regulatory framework, it said, was a mechanism to provide early warning of pending trouble in financial institutions.
“Laws should require supervisory agencies to provide effective early warning mechanisms and to take prompt corrective actions to minimise the risk of financial crisis,” the report said.
Amongst other considerations, bankruptcy and foreclosure laws had to be amended to help seize debtors’ assets and reduce the need to resort to the
Continued on next page
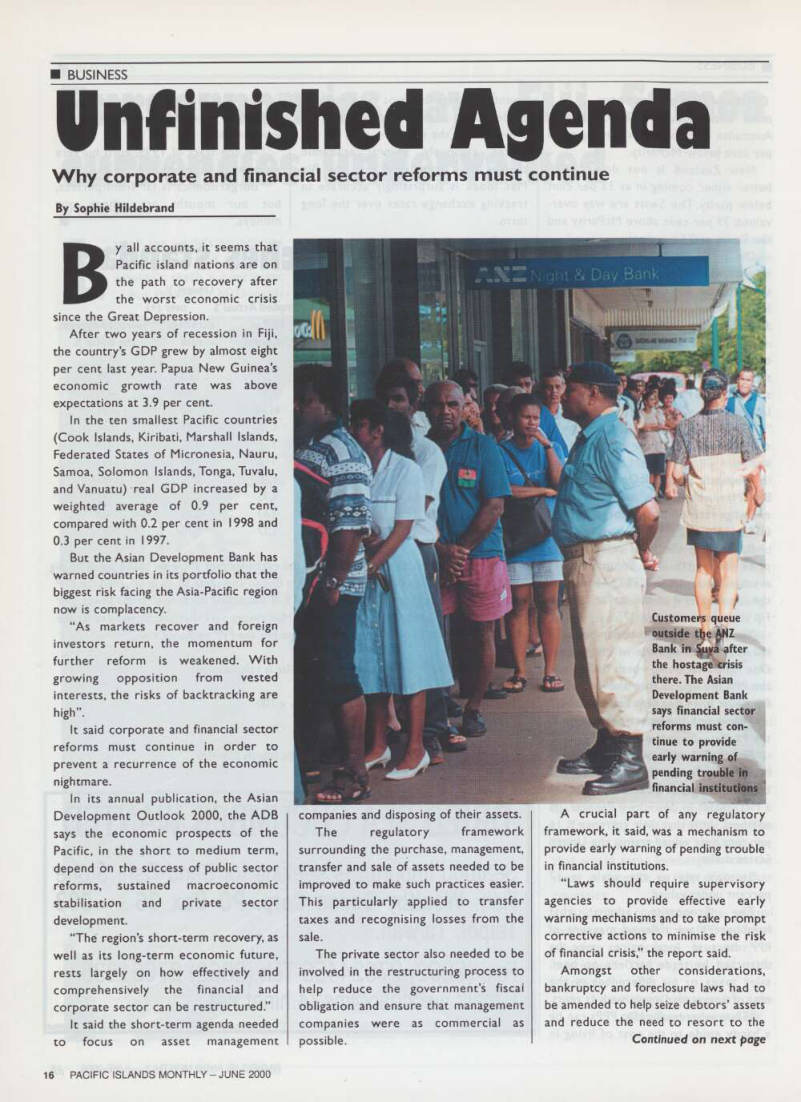
Customers queue outside the ANZ Bank in Suva after the hostage crisis there. The Asian Development Bank says financial sector reforms must con tinue to provide early warning of pending trouble in financial institutions
Continued from previous page
judicial process.
As well, the report said bank secrecy laws may have to be loosened to increase financial transparency and discourage corrupt funds flowing through the financial centres.
Attacking poor governance has also been recommended to increase transparency of economic and financial data, strengthen corporate disclosure requirements, increase accountability to shareholders, strengthen competition laws, privatise state-owned enterprises, and dismantle state-supported monopolies and cartels.
Privatisation of public assets will not guarantee improved welfare of the masses, but has the upside of stamping out government corruption and raising the necessary funds to repay debts, according to World Bank PNG resident coordinator Daniel Weise.
Weise said while there was no guarantee that privatisation would bring improved welfare, it provided an opportunity for this to happen, but only if all the processes and systems have been set right.
He said the World Bank is very determined to get the necessary reforms in place so that the sale of public assets resulted in effectively run and transparent organisations.
He said privatization is a more difficult option than undertaking macroeconomic adjustments but, with full commitment from the government, it can be achieved.
He said experience from elsewhere around the world points to positive results from privatisation moves.
As well, by privatising nationalised banks and state-owned enterprises, additional revenue could be generated to remedy fiscal imbalances.
ADB says it is generally agreed that one of the major causes of the Crisis was “excessive reliance on short-term bank loans from abroad to facilitate long term investments at home and abroad”.
It says there is a need to modernise
and develop capital markets, particularly
bond markets, and maximise the efficiency with which long-term savings
are channelled into profitable industrial and infrastructure projects.
To do this a financial sector blueprint was needed, covering the banking sector, nonbank credit organisations, insurance sector, capital markets and newer financial institutions such as venture
capital entities.
ADB recommends that all types of long-term financial markets be fostered, including equity, bond and insurance.
It said first a market for primary government securities issues must be
developed, followed by a secondary
market for such issues and then a corporate bonds market will develop.
The Governor of the Solomon Islands’ Central Bank, Rick Hou, says the country’s external debt arrears remain at more than $lB million.
However, he says the Solomons’
Government is on track with its debt servicing.
He said nearly $8 million of the amount is in interest alone.
The loans are with the Marubeni Bank
of Japan and the Ethical Fund for Insurance Corporation in Australia.
The Central Bank Governor said the EFIC loan and its arrears were restructured early this year and the interest rate has been reduced to three percent.
Mr. Hou also said that the Solomon Islands must try to reduce its reliance on overseas assistance as it develops.
The financial sector, ADB says, was the weakest link in Asian economies.
“Excessive government intervention, overreliance on banks, and pervasive
crony capitalism hampered innovation
and distorted incentives.”
The public sector, it says, must play an important role in overcoming coordination failures and setting
regulatory standards.
But, it should not become directly involved in allocating capital.
This, ADB says, is most efficiently and safely done by a diverse and largely private financial system within proper regulatory framework. ■